All Categories
Featured
A bipartisan group of legislators has introduced legislation to break down on deceptive practices utilized by fraudulent credit repair work organizations.The Ending Fraud Credit Repair Work Act, or ESCRA, by Sens. Chris Coons( D-Del. )and Lisa Murkowski( R-Alaska) would enhance defenses for consumers by forbiding credit repair companies from gathering payment until 6 months after they have actually offered evidence that a consumer's credit history has actually enhanced, according to the sponsors. A buddy costs( H.R. 306) was presented in the Home by Reps. Sarah McBride( D-Del.) and Young Kim( R-Calif. ). In a statement in assistance of the legislation, Kirsten Sutton, EVP of congressional relations and legal affairs at the American Bankers Association, kept in mind that banks help customers construct credit through transparent products, financial education and long-term assistance, "and this essential legislation reinforces those accountable pathways by targeting misleading credit repair schemes."" ABA has actually regularly supported efforts to enhance customer confidence in the credit system, and we applaud Senators Coons and Murkowski, and Representatives McBride and Kim, for their management in working to ensure consumers are secured, "Sutton said. The project will gear up both customers and bank volunteers with dependable details, useful tools and skilled insights, including advice on how to identify misleading credit repair organizations.( Article Updated Jan. 6 and 8, 2026) This post notes federal and state consumer law changes arranged to enter into effect or expire throughout the duration from December 1, 2025, through January 1, 2027. Other consumer law changes will be enacted in 2026 and will enter into impact in 2026; this post notes modifications whose effective dates have currently been scheduled as of December 31, 2025. NCLC motivates readers to send( to) extra customer law changes efficient in 2026, especially changes in state customer legislation. NCLC will add suitable submissions to this article. Important changes to Personal bankruptcy Rule 3002.1 and six associated new bankruptcy kinds went into impact on December 1, 2025. The modifications protect house owners who utilize chapter 13 personal bankruptcies to fend off foreclosures and keep themselves current on their home loans, offering them details required to effectively complete a treatment plan and emerge from chapter 13 without surprise, concealed costs, or payment quantities due. New Guideline 8006( g) will clarify that any celebration to an appeal might file a request that a court of appeals authorize a direct appeal. 26 U.S.C. 108( a) provides that specific forgiveness on a home mortgage loan is ruled out income for income tax functions, but the Qualified Principal Residence Indebtedness Exemption from Income expired at the end of 2025. Although other exemptions from taxability of forgiven debt might use, this exemption no longer applies. The American Rescue Strategy Act briefly eliminated federal earnings tax effects for all federal student loan discharges and cancellations that happened in between January 1, 2021, and December 31, 2025. See. This exclusion has actually not been extended, and the quantities discharged or cancelled from federal student loans starting on January 1, 2026, may count toward gross income unless another exemption applies. See( Dec. 15, 2025 ). This exemption does not use to home-secured credit or student loans. See. On January 1, the adjusted total loan quantity limit for high-cost home loans increases from $26,968 to$ 27,592, and the adjusted points and fees dollar trigger for high-cost home mortgages increases from$ 1,348 to $1,380. 15, 2025 ). See. To identify whether a covered transaction is a qualified home mortgage( QM), the overall points and charges charged might not go beyond the limit set for the size of the loan. Reliable January 1, 2026, these limits increase. For QMs under the basic QM loan meaning in 12 C.F.R. For all classifications of QMs, the limits for total points and fees in 2026 will be 3% of the overall loan amount for a loan higher than or equal to$ 137,958;$ 4,139 for a loan amount greater than or equivalent to$ 82,775 however less than$ 137,958 ; 5% of the total loan quantity for a loan higher than or equal to$ 27,592 however less than$ 82,775;$ 1,380 for a loan amount greater than or equal to $17,245 but less than $27,592; and 8% of the total loan amount for a loan quantity less than $17,245. 15, 2025 ). See usually. Reliable January 1, the exemption threshold for special appraisal requirements for "higher-risk mortgages "increases from $33,500 to $ 34,200. See (Dec. 16, 2025). See likewise. Reality in Loaning Reg. Z, 12 C.F.R. 1026.6 (b) (2)( iii )and 1026.60( b)( 3) need creditors to divulge any minimum interest charge going beyond $1.00 that might be imposed throughout a billing cycle. 7, 2026). Reliable January 1, 2026, banks, savings associations, and cooperative credit union with properties of $59 million or less as of Dec. 31, 2025, are exempt from gathering information in 2025( the old limit was $58 million ).( Jan. 7, 2026). The CRA asset limits for certain exemptions are increased as of January 1, 2026, so that "little bank "means a bank that, as of December 31 of either of the previous two fiscal year, had assets of less than$ 1.649 billion. See( Jan. 7, 2026). Efficient January 1, 2026, the optimum charge to a consumer under the FCRA for file disclosure is$ 16.00, up from$ 15.50. (Dec. 15, 2025 ). Consumers are also entitled to specific free disclosures, consisting of complimentary weekly file disclosures from Equifax, Experian, and TransUnion. See. On January 1, 2026, the Consumer Leasing Act exemption for customer leases surpassing a total legal obligation quantity is increased from$ 71,900 to$ 73,400. 15, 2025). See likewise. FHA has revealed brand-new loan limits for 2026. The single-family, low-cost-area ceiling increases to $541,287 and the high-cost-area ceiling increases to$ 1,249,125. See( Dec. 11, 2025). For HECM reverse mortgages the optimum claim amount increases on January 1 to $1,249,125. See (Dec. 11, 2025). Theconforming loan limitations for 2026 for Fannie Mae and Freddie Mac mortgages. In many of the United States, the 2026 worth for 1-unit residential or commercial properties will be$ 832,750. For locations in which 115% of the regional mean home value goes beyond the baseline adhering loan limitation value, the relevant loan limitation for 1-unit residential or commercial properties will be$ 1,249,125.
Arizona has a brand-new lawsuits funding statute,, effective January 1 2026. requires self-storage rental agreements at first got in into on or after January 1, 2026, to reveal, in a proposed manner, whether the rental charge is marked down or promotional, whether the rental charge is subject to alter, and the optimum rental fee that.
the owner might charge throughout the first 12 months following the date of the rental contract., effective January 1, 2026, requires a social networks platform to provide a clear and obvious button that makes it possible for the user to delete their account and provide the user with the required steps to delete the user's account and personal details. The expense forbids a social.
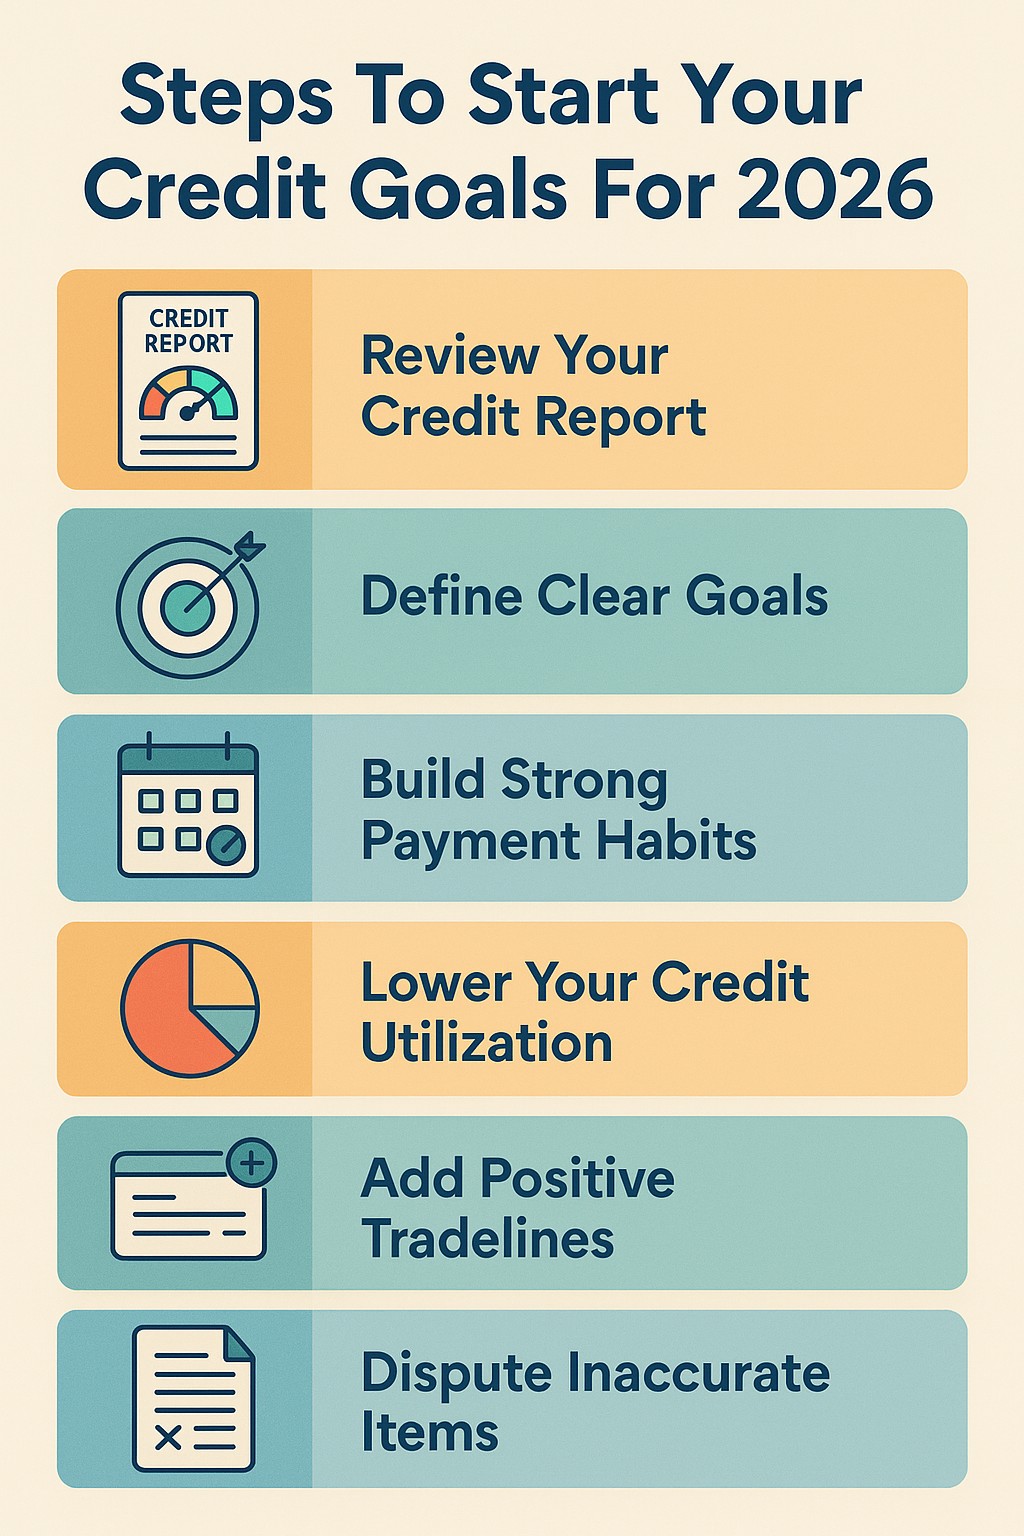
Boosting Personal Credit Health for New Successmedia platform from blocking or hindering a user's ability to erase their account., efficient January 1, 2026, loosens up evidence requirements for a cost repairing claim under state law and prohibits use or distribution of a common pricing algorithm as part of a price fixing plan. also significantly increases civil and criminal penalties for infractions of the state anti-trust law.
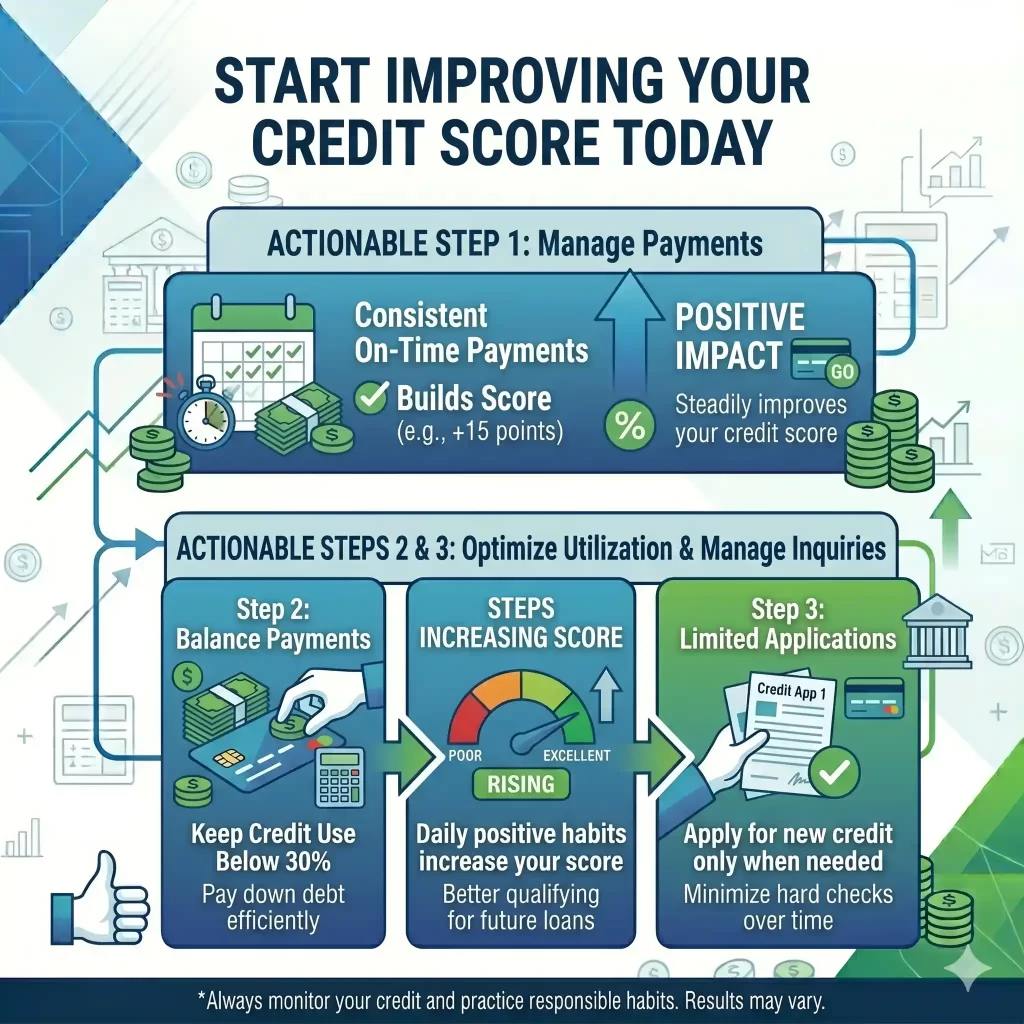
Understanding Legal Laws in New Statutes
efficient January 1, 2026, forbids a defendant who developed, modified, or utilized expert system from asserting a defense that the synthetic intelligence autonomously triggered the damage to the plaintiff. The food delivery platform must also provide a customer care feature that allows a customer to contact a natural person., efficient January 1, 2026, prohibits a person from advertising pricing for a good, service, or residential or commercial property unless the person plainly and notably discloses the optimum overall of all amounts that an individual may pay, although government and shipping charges can be excluded. A violation is a state UDAP violation. On January 1, 2026, (2024), goes into result extending Colorado's right to fix laws to certain electronic devices, including mobile phone, computer systems, and televisions. A maker of digital electronic equipment need to facilitate the repair work of its devices by providing certain other persons with the resources needed to repair the producer's digital electronic devices. The changes cover almost every post of the UCC and include a new Article 12 resolving certain types of digital properties specified as "Manageable Electronic Records. "The modifications likewise clarify the UCC's applicability to mixed transactions involving both products and services. The amendments likewise contain some miscellaneous revisions unassociated to technological advancements that impact consumer transactions. See. Thirty-three jurisdictions have now adopted the 2022 changes. Georgia has a new litigation financing statute,, regulating foreign third-party lawsuits funders that enters into effect on January 1, 2026., effective January 1, 2026, offers different securities for domestic partners whose partner pushes them to take on financial obligation, whether by force or scams. One piece of precious jewelry up to$ 5,000 is exempt. Reliable January 1, 2026, offers that when it comes to a consumer financial obligation judgment entered upon or after January 1, 2020,$ 1,000 of the$ 4,000 wild card is instantly applied to the judgment debtor's interest in a monitoring or cost savings deposit account. efficient January 1, 2026, the Indiana information privacy statute enters into result, establishing comprehensive brand-new data privacy requirements.( May 1, 2023 )., efficient January 1, 2026, is a partially industry-sponsored expense that secures earned wage payday loans, but consists of some consumer securities, restricting making speed up fees the default option, or recommending a default tip higher than absolutely no, and likewise needs the service provider, if a consumer elects a no-cost option, to start the shipmentof the earnings not later than one organization day.( 2024). Starting January 1, 2026, the base optimum cost is adjusted every year to the lower of (1)$ 425, changed by inflation or( 2) the amount arising from applying a development rate of 3 percent to the changed maximum charge for the previous calendar year. The Louisiana Automobile Commission will release the adjusted optimum charge on its official site. On January 1, 2026, the maximum loan processing fee on installment loans will change from the existing$ 400. See In re, Publication 2024-05-CF (Mich.

Latest Posts
Key Consumer Rights Under 2026 Credit Repair
Ways to Increase Credit Score Fast 2026
Locating Credit Counseling Near Me 2026